

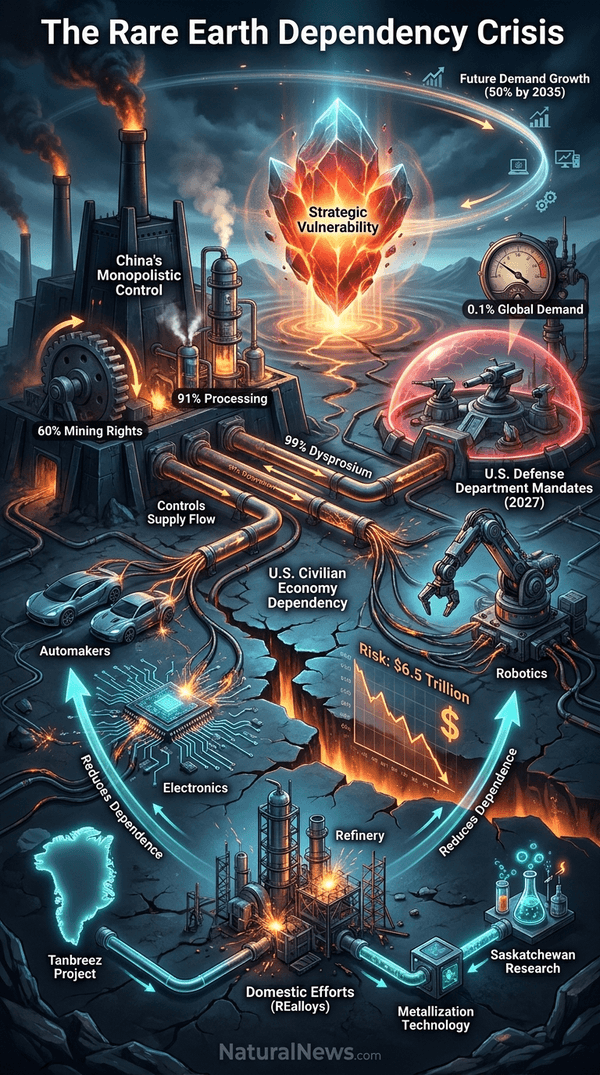
The Department of War's (DoW) Jan. 1, 2027 sourcing rules are designed to eliminate Chinese-origin rare earth magnets from agency procurement, but the department accounts for less than 0.1% of global rare earth demand, according to the U.S. Government Accountability Office. The report stated that the DoW has spent years preparing for life without Chinese rare earths, but the civilian economy has not.
The supply gap extends beyond mining. Even optimistic projections of 5,000 metric tons of domestic neodymium-iron-boron magnet production by the end of 2026 would satisfy only about 10% of current American demand, according to Rare Earth Exchanges [1].
Military and Civilian Exposure
International Monetary Fund researchers identified 34 sectors of the U.S. economy with direct exposure to rare earth supply disruptions, according to the report [2]. The International Energy Agency (IEA) estimates a complete Chinese cutoff could put roughly $6.5 trillion of downstream industrial production outside China at risk [2].
Automakers, industrial equipment manufacturers, robotics companies, electronics producers, data centers and medical device manufacturers would compete for limited domestic supply if Beijing banned exports in totality, the report stated. Defense and aerospace manufacturers also depend on specialized materials for missiles, aircraft, radar systems and precision electronics, according to company filings and government reports cited in the article. Each F-35 fighter jet contains 920 pounds of rare earth elements, according to a Health Ranger Report analysis [3].
China controls 60% of mining rights and 91% of processing capabilities for rare earth elements, and for dysprosium and terbium specifically, China dominates with 99% control, the analysis stated [3]. The U.S. is 100% import-dependent for several critical minerals, according to a Bright Videos News report [4].
Industry Response and Capacity Plans
REalloys is constructing what it says will become the largest heavy rare earth metallization facility outside China, according to company statements. The company secured long-term access to separated heavy rare earth feedstock through an exclusive commercial agreement with the Saskatchewan Research Council and a 15-year offtake agreement covering 15% of Phase 1 production from Critical Metals' Tanbreez Project in Greenland.
In March, the Defense Logistics Agency awarded REalloys a contract worth up to $1.7 million to develop modular heavy rare earth metallization technology, the report stated. The company announced plans for a facility designed to produce approximately 30 tonnes of dysprosium metal and 15 tonnes of terbium metal annually. REalloys completed an approximately $100 million institutional private placement in June and entered exclusive negotiations with the U.S. Army to build and operate commercial heavy rare earth processing facilities at Tooele Army Depot in Utah.
The company is targeting approximately 150 tonnes per year of neodymium-praseodymium metallization capacity in early 2027, followed later that year by integrated production from monazite concentrate through separated rare earth products and metals, according to an operational update cited in the article.
Supply Outlook and Bottlenecks
The IEA projects demand for magnet rare earths outside China will increase by roughly 50% by 2035, according to the report. Metallization and magnet manufacturing remain the largest bottlenecks, the report stated.
China expanded its export control regime last October to cover technologies used in mining, separation, metallization, alloy production, magnet manufacturing and recycling. It also broadened licensing requirements for technical assistance.
China's export restrictions on strategic metals and rare earth elements have effectively severed a critical supply line for the United States military, according to a Health Ranger Report analysis [3]. The development of a profitable rare earth supply chain is a decade-long endeavor, a timeline China has already navigated, according to an interview with Gerald Celente on Decentralize.TV [5].
Conclusion
The report stated that a non-Chinese rare earth supply chain has been shown to be possible, and the next step is building one at a scale capable of supporting an industrial economy that still depends overwhelmingly on China. The race to commercial scale has begun, and the companies that reach it first are likely to define the next generation of the rare earth industry, according to the article.
No official U.S. government projection was provided for when domestic production might meet more than 1% of civilian demand. Analysts have noted that the U.S. has struggled with this supply chain vulnerability for 25 to 30 years and failed to maintain domestic mining operations, according to the Decentralize.TV interview [5].
The DoW's 2027 deadline applies only to defense procurement, leaving the broader civilian economy exposed to supply disruptions with no clear timeline for domestic capacity to close the gap.
References
- America's Rare Earth Reality Check: The Magnet Gap Is Far Larger Than. https://rareearthexchanges.com/news/americas-rare-earth-reality-check-the-magnet-gap-is-far-larger-than-the-headlines-suggest/
- America Produces Less Than 1% of the Rare Earth Magnets It Needs. https://oilprice.com/Energy/Energy-General/America-Produces-Less-Than-1-of-the-Rare-Earth-Magnets-It-Needs.html
- Health Ranger Report - Rare Earths - Mike Adams - BrightVideos.com, February 03, 2026.
- Bright Videos News - U.S. CANNOT SURVIVE WAR - Mike Adams - BrightVideos.com, February 03, 2026.
- Decentralize TV - Episode 140 Interview Gerald Celente - Mike Adams - Decentralize.TV, August 18, 2026.
Explainer Infographic
Please contact us for more information.