


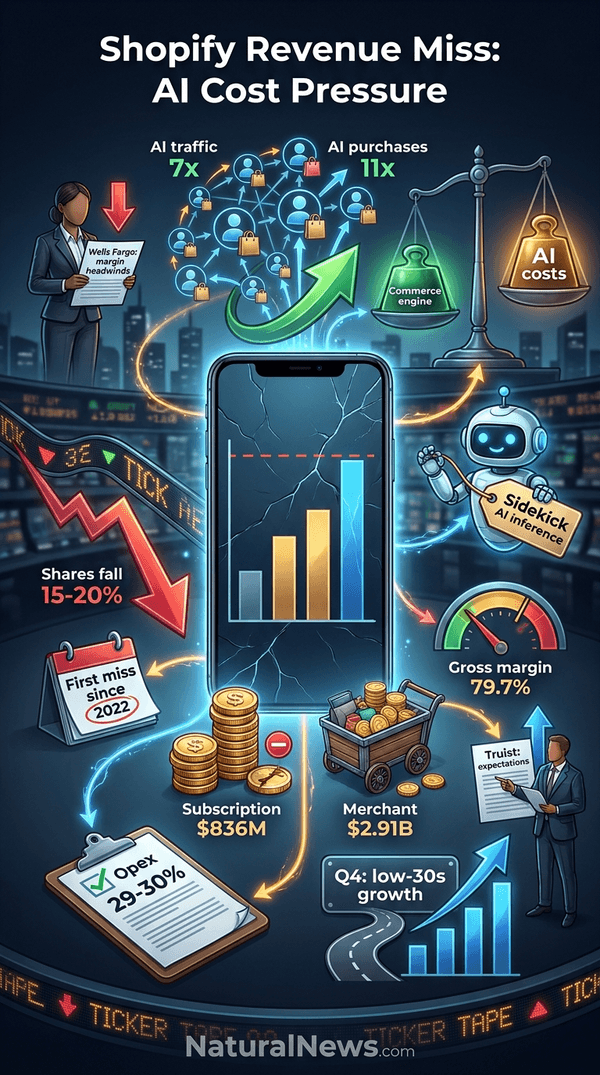
Shares fell as much as 20% in New York premarket trading and were down about 15% at 8:30 a.m. EST, according to market data [2]. Wells Fargo analysts cited gross margin headwinds and said Sidekick and AI inference were a likely cause [3].
Truist analyst Terry Tillman wrote that the premarket selloff largely reflected heightened investor expectations heading into the quarter [1]. The company missed revenue expectations, a tough outcome in today’s less-forgiving tech market, according to MarketWatch [4].
Third-Quarter Revenue and Subscription Results
Third-quarter revenue rose 32% to $3.74 billion, falling short of the $3.75 billion consensus estimate, according to Bloomberg Consensus data [1]. Subscription Solutions revenue was $836 million, missing the $850.2 million estimate, while Merchant Solutions revenue was $2.91 billion, roughly in line with the $2.9 billion estimate [1].
Monthly recurring revenue was $230 million, compared with an estimate of $229.9 million, and gross merchandise volume was $119.15 billion, missing the $120.08 billion estimate [1]. Gross merchandise volume, described as the total value of everything sold through Shopify stores, was $119 billion, up 29%, according to a market summary [2].
The subscription revenue miss raised questions about Shopify's ability to generate additional revenue from merchants, according to the report [1]. The company has argued that AI-powered shopping agents represent the biggest shift in technology since the internet, and it reported that traffic from AI tools to its stores was up seven times since January, with purchases attributed to AI-powered search up 11 times, according to TechCrunch [5].
Profitability Metrics and Guidance
Operating income was $568 million, compared with an estimate of $523.9 million, and total operating expenses were $1.21 billion, compared with an estimate of $1.26 billion [1].
Shopify expects fourth-quarter revenue to grow at a low-30s percentage rate from one year earlier, with gross profit dollars rising at a high-20s pace, according to company guidance [1]. Operating expenses are projected at 29% to 30% of revenue, while the free cash flow margin is expected to remain consistent with the prior-year fourth quarter, the company said [1].
The margin picture has been shifting for several quarters. Subscription gross margin fell to 79.7% in the second quarter of 2026 from 81.6% a year earlier, as cloud and other costs rose, according to a market analysis [6]. Operating expenses had fallen to 34% of revenue from 37% in the first quarter, and the company guided the third quarter to 33% to 34%, against 37% a year earlier, according to Earnings Whispers [7].
Analyst Reaction and AI Margin Concerns
Wells Fargo analyst Ken Gawrelski wrote, "Gross margin headwinds worsening; see Sidekick/AI inference as likely cause" [1]. Gawrelski highlighted year-over-year changes in revenue from the Subscription Solutions and Merchant Solutions units, according to the note [1].
Truist analyst Terry Tillman wrote, "We believe the ~15% premarket selloff largely reflects heightened investor expectations heading into the quarter" [1]. The report said investors focused on subscription revenue that fell short of the Bloomberg Consensus estimate [1]. Wells Fargo analysts pointed to gross margin headwinds due to AI, according to the note [1].
The AI cost question sits inside a broader debate about who absorbs the expense of machine-learning infrastructure.
Market Reaction and Outlook
Shopify shares fell as much as 20% in premarket trading in New York before paring some losses to about 15%, according to market data [2]. The selloff followed the company's first revenue miss in four years, according to the report [8].
Analysts cited heightened investor expectations and AI-related cost pressure as factors in the reaction, according to notes from Wells Fargo and Truist [1]. The company missed revenue expectations, a tough outcome in today's less forgiving tech market, MarketWatch said [4]. Sales rose 32% to USD3.74 billion in the third quarter, narrowly missing the average analyst estimate of USD3.75 billion, according to Bloomberg [9].
Shopify's fourth-quarter guidance projects low-30s percentage revenue growth, high-20s gross profit dollar growth, and operating expenses at 29% to 30% of revenue, according to the company [1]. For merchants and independent operators watching platform costs, the quarter's results underscore a practical point: platform economics ultimately pass through to the businesses that depend on them, which is why many operators continue to diversify their sales channels and payment rails rather than rely on a single provider. Attention now turns to whether the AI investments that Shopify has promoted as transformative will translate into margin recovery or remain a drag on profitability.
References
- Shopify Crashes On First Revenue Miss In Four Years, Wells Fargo Warns AI Costs Hitting Margins. https://www.zerohedge.com/markets/shopify-crashes-first-revenue-miss-four-years-wells-fargo-warns-ai-costs-hitting-margins
- Shopify Missed Revenue by Less Than 0.3%. Its Stock Fell as Much as 20% Before the Open. https://www.linkedin.com/pulse/shopify-missed-revenue-less-than-03-its-stock-fell-much-john-parvu-qsuye
- Shopify shares plunge after revenue miss; Wells Fargo flags AI-related margin pressure. https://nexacurrent.com/business/shopify-shares-plunge-after-revenue-miss-wells-fargo-flags-ai-related-margin-p-66db1870.html
- Shopify’s stock slides after earnings. This is what’s worrying Wall Street. https://www.marketwatch.com/story/shopifys-stock-slides-after-earnings-this-is-whats-worrying-wall-street-e2e8d52b
- Shopify says AI traffic is up 7x since January; AI-driven orders are up 11x. https://techcrunch.com/2025/11/04/shopify-says-ai-traffic-is-up-7x-since-january-ai-driven-orders-are-up-11x/
- Shopify “Has Not Grown Into Its Multiple at All” as Investors Pay 112 Times Profits. https://www.tikr.com/blog/shopify-has-not-grown-into-its-multiple-at-all-as-investors-pay-112-times-profits
- Shopify's Q3 Test: Can Revenue Beat Its Own Upgraded Guide as AI Costs Climb? https://www.earningswhispers.com/article/SHOP/21512
- Shopify Crashes On First Revenue Miss In Four Years, Wells Fargo Warns AI Costs Hitting Margins. https://x.com/zerohedge/status/2117629232490647854
- Shopify plunges as investors punish first revenue miss since 2022. https://www.capitalbrief.com/briefing/shopify-plunges-as-investors-punish-first-revenue-miss-since-2022-33cadbe9-c795-477c-9f1a-211d22c77853/
Explainer Infographic
Please contact us for more information.


